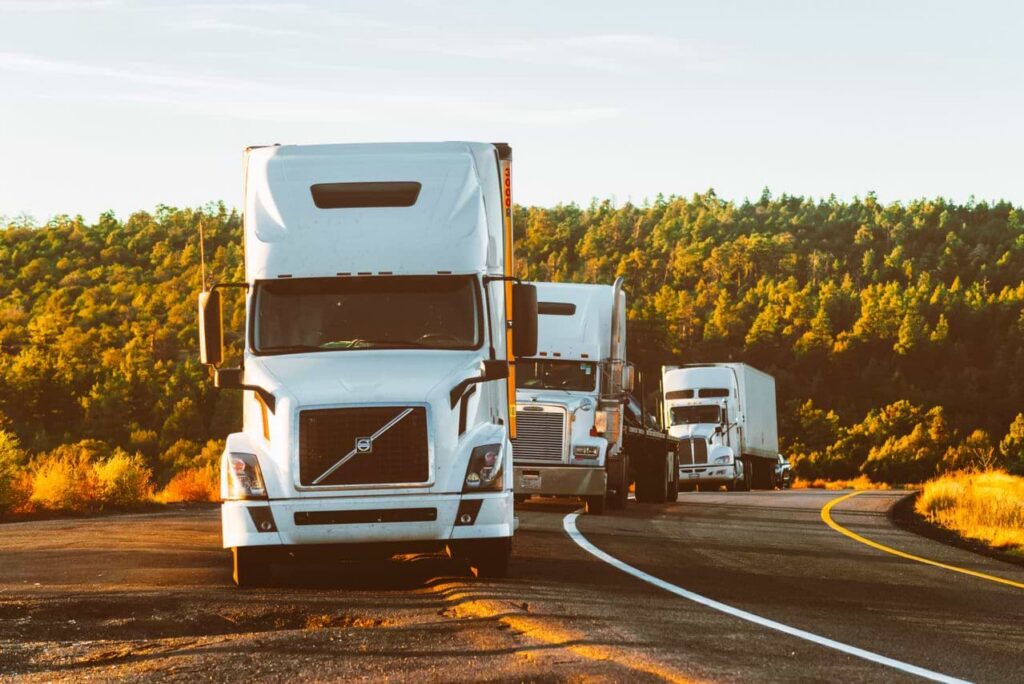
Navigating the open road as an owner-operator brings freedom, but it also carries significant risk. From unexpected accidents to freight damage and regulatory fines, single missteps can endanger your livelihood. Securing the right commercial truck insurance isn’t just a legal necessity—it’s the backbone of your business stability.
What Primary Policies Every Trucker Needs
Not all trucking insurance policies are created equal. Depending on whether you operate under your own authority or are leased to a motor carrier, your coverage requirements will vary.
- Primary Auto Liability: Mandatory by federal law. This covers bodily injury and property damage to others if you are involved in an at-fault accident.
- Physical Damage Coverage: Protects your truck and trailer against perils such as collisions, rollover, theft, fire, or vandalism.
- Motor Truck Cargo Insurance: Covers the financial value of the freight you are hauling in the event of damage or loss during transit.
- Non-Trucking Liability (Bobtail Insurance): Provides liability protection when using your truck for non-business or personal reasons off-duty.
3 Smart Strategies to Lower Your Premium Rates
- Maintain a Clean Driving Record: Safe driving logs directly correlate to lower risk scores and reduced premium rates.
- Invest in Telematics & Safety Features: Installing dash cams and speed limiters shows insurers proactive risk management.
- Choose the Right Deductible Balance: Opting for a higher deductible can lower your monthly premium, provided you keep an emergency reserve fund for claims.
At Insured by Schulz, we work with top-tier carriers like Sentry, Great West, and Cover Whale to tailor custom coverage packages designed for independent truckers and fleet managers alike.